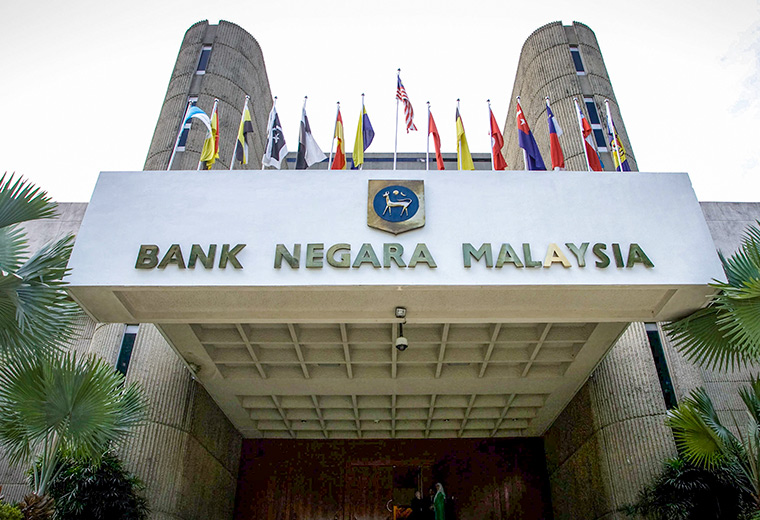
MALAYSIAN SMEs and selected business sectors are coming under growing financial pressure from the Middle East conflict as higher energy, logistics and input costs squeeze margins and cash buffers, although the country’s financial system remains resilient, Bank Negara Malaysia (BNM) said.
The central bank said Malaysia’s deep integration with global trade and financial markets meant the conflict could generate significant spillovers, primarily through indirect channels despite limited direct financial exposure to the Middle East.
It said the pressures were most evident among SMEs, particularly those in transportation, wholesale and retail trade and primary manufacturing, where thinner margins, smaller liquidity buffers and greater reliance on short-term financing left businesses more exposed to prolonged cost pressures.
“Nevertheless, the implications for domestic financial stability have remained manageable,” it said.
BNM said business conditions had remained broadly stable, supported by sustained domestic demand, strong electrical and electronics exports and continued investment activity.
However, businesses had reported higher input and logistics costs, delayed payments and longer cash-conversion cycles, while some had seen their cash buffers decline.
The pressures could weaken corporate margins and borrowers’ ability to service debt if sustained, while higher costs could also feed through to households by eroding purchasing power and raising debt-servicing pressures.
Primary manufacturers, meanwhile, have faced higher costs for inputs including fertiliser and petrochemical-related commodities, although most firms have continued to secure essential supplies at higher prices.
Businesses have responded by improving cost efficiency, diversifying suppliers, adjusting production and inventory levels and strengthening cash-flow management.
BNM said these measures had so far helped contain the impact on corporate financial positions and preserve borrowers’ ability to service their debts.
The overall quality of business borrowings also remained sound, with the business loan impairment ratio at 2.8% as at June 2026.
The proportion of loans classified as having increased credit risk, or Stage 2 loans, also remained below its near-term average.
Nevertheless, BNM said repayment pressures had emerged among selected business segments, particularly SMEs in transportation, wholesale and retail trade and primary manufacturing.
“These developments point to the possibility of latent credit risk building up among selected firms experiencing persistent liquidity pressure,” it said.
Beyond businesses, the central bank said the conflict could affect domestic financial stability through weaker global demand, supply disruptions, inflation and heightened market uncertainty.
Risk-off sentiment could also trigger shifts in investment portfolios and capital flows, affecting asset valuations, bond yields, exchange rates and market liquidity.
The combined effects could eventually tighten credit and funding conditions and raise credit and claims costs, valuation losses and funding and liquidity pressures for financial institutions.
BNM, however, said banks, insurers and takaful operators continued to maintain strong financial buffers, while deep domestic financial markets and a diversified investor base had helped contain external volatility.
“Evidence so far indicates that the risk of such interactions amplifying financial stress has remained limited, with the financial system absorbing the shocks with a high degree of resilience,” it said.
BNM said continued monitoring at both borrower and sector levels remained important as the external risks evolved. - October 5, 2026