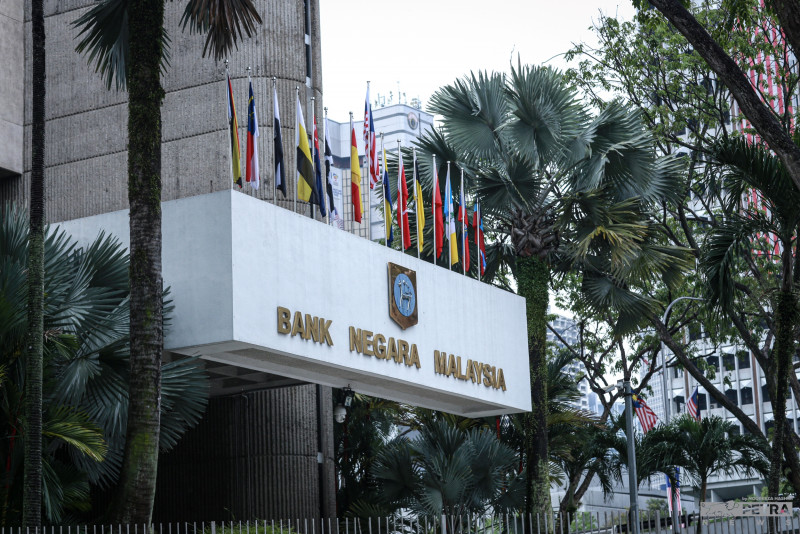
BANK Negara Malaysia (BNM) wants Islamic financial institutions to play a greater role in financing Malaysia’s economic transformation, with the goal set to feature prominently in a new financial sector blueprint scheduled for launch in 2027.
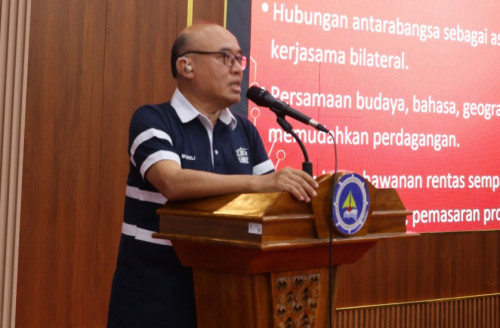
BNM Governor Datuk Seri Abdul Rashid said that the blueprint would focus on expanding Islamic finance, accelerating innovation, strengthening the financial ecosystem and deepening Malaysia’s international financial connections.
“Islamic finance must play a central role in supporting Malaysia’s economic transformation. This includes mobilising capital and providing solutions for strategic growth areas such as the green transition, the halal economy, and the development of high-value-added industries, including the electrical and electronics ecosystem,” he said.
He said innovation should be measured by its real-world impact rather than the number of financial products introduced.
“The true measure of Islamic finance is not the number of products launched, but the actual impact these solutions have on businesses, communities and the economy as a whole,” he said.
Abdul Rashid said Islamic finance should also improve social well-being by strengthening household financial security, supporting businesses and making the economy more inclusive and resilient.
“The next phase of Islamic finance is not just about scale, but also about influence,” he said, adding that its success should be reflected in better livelihoods, greater financial security and a greener future.
Other priorities include establishing Malaysia as an international gateway for Islamic finance, making value-based finance mainstream, strengthening impact assessments, deepening Islamic financial markets and liquidity, and encouraging the use of a wider range of Shariah contracts.
On the entry of foreign Islamic banks, Abdul Rashid said Malaysia remained open to new participants that could make a meaningful contribution to the economy.
“We have never closed our doors. Therefore, any new entrant will be evaluated based on its ability to bring additional capabilities and its potential to support the needs of emerging economies,” he said.
On banking consolidation, he said BNM would maintain a market-driven approach while supporting the development of stronger financial institutions capable of meeting the financing needs of businesses, households and the wider economy.
He highlighted the green economy, halal industry and semiconductor sector as areas where financial institutions could provide funding to support growth and economic transformation.
Malaysia continued to hold a significant position in global Islamic finance, with Islamic capital market activity accounting for about 64 per cent of the country’s total capital market activity in 2025.
The country also accounted for approximately 31.5 per cent of outstanding Islamic bonds worldwide.
Abdul Rashid said investor demand for Malaysia’s US$1.5 billion global sukuk issuance demonstrated continued confidence in the country’s Islamic finance capabilities.
The issuance was oversubscribed 4.7 times, with total orders exceeding US$9.5 billion at one point.
He said demand was strong and pricing spreads reached record lows, with the 5.75-year sukuk priced 15 basis points above the US Treasury benchmark and the 10-year tranche priced 25 basis points above it.
He added that Malaysia’s borrowing spreads were comparable to those of sovereign issuers rated AA, despite the country having an A credit rating, reflecting its ability to extend its domestic expertise in Islamic finance to international markets.
On technological development, Abdul Rashid said artificial intelligence (AI) and digitalisation should be adopted responsibly to improve access to financial services and broaden financial inclusion.
“We want innovation to be responsible and to benefit businesses, families, borrowers, the economy as a whole, and the nation. It must protect the interests of our customers. More importantly, it must create real value for the economy,” he said.
He identified the use of alternative data and behavioural assessments to evaluate borrowers with limited credit histories as an area with significant potential to expand access to formal financing.
He cited Malaysia’s digital Islamic banks, AEON Bank and KAF Digital Bank, as examples of institutions using technology to assess customers’ repayment behaviour and extend financing to groups previously underserved by the financial system.
Beyond financial inclusion, he said technology could improve capital allocation, direct financing towards productive businesses, reduce transaction costs and support the country’s economic transformation. - October 26, 2026