MOST Malaysians spend the greater part of their lives either financially dependent or drawing down savings, with only a limited 26-year period in which income meaningfully exceeds expenditure, according to newly released data from the Department of Statistics Malaysia (DOSM).
The findings, based on the National Transfer Accounts 2022, show that surplus income is typically generated only between the ages of 29 and 55, underscoring a narrow window for wealth accumulation amid mounting cost-of-living pressures.
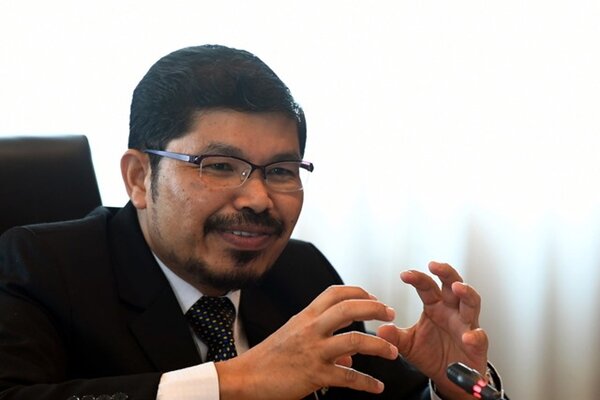
Chief Statistician Datuk Seri Mohd Uzir Mahidin described the pattern as a defining feature of the country’s financial lifecycle.
“That period is about 26 years — your strongest earning phase which is why you must use this window wisely with spending and delaying consumption now to increase your surplus for the future,” he said at the report’s launch.
The analysis tracks how labour income compares with consumption across different stages of life, revealing prolonged deficit phases at both the beginning and end of the lifecycle, with a relatively brief surplus period in between.
From birth to the late twenties, Malaysians remain in a “life cycle deficit”, where consumption exceeds income and is largely supported through family assistance and public spending, particularly in education.
Even as individuals enter the workforce, financial pressures persist.
“There is a physical deficit at ages 20 to 28, where individuals are unable to save because spending needs are still high,” Uzir said.
A shift occurs at age 29, when earnings begin to outpace spending, marking the start of a productive phase that lasts until age 55. This period forms the backbone of economic contribution, both within households and across society.
At its peak, annual surplus income reaches RM14,523 per person at age 44.
“This surplus is not just for yourself — it is transferred to support other age groups,” he said.
However, the advantage is short-lived. From age 56 onwards, declining labour income pushes individuals back into deficit, with consumption increasingly sustained through savings, investments and transfers.
“As labour income reduces, individuals depend more on assets and support systems to sustain consumption,” he said.
The findings, Uzir stressed, highlight the critical importance of early and sustained financial planning, particularly in avoiding lifestyle inflation during peak earning years.
“Saving is about delaying current consumption for future use,” he said. “But it must be done wisely, especially with inflation in mind.”
“Those just starting work — buying expensive cars — it reduces your surplus. You should continue to invest so you have savings at the end,” he added.
Beyond structural trends, Uzir pointed to a cultural shift in financial behaviour, noting that traditional saving habits have weakened with the rise of digital payment systems.
“When we were in school, there was already a concept of saving. Teachers would bring stamp books, and if we didn’t spend our money, we would paste the stamps and save. At the time, there weren’t many banks around.
“We’d then take those books to the post office, either on our own or with our parents, to deposit the accumulated value or surplus in the city.
“That was how we built the habit — collecting, saving, and keeping money in the post office.
“Has anyone here done that or maybe I’m just the old one here,” he said.
While financial tools have evolved, he emphasised that the underlying discipline required for saving remains unchanged.
“Saving is delaying current consumption but it must come with a condition — inflation must be controlled. If inflation is too high, then delaying spending becomes less meaningful.”
He added that even modest investment returns can provide meaningful support over time.
“If you are financially literate and can get returns of more than 10 per cent, that’s good,” he said.
“However, not everyone can do that. You need to be savvy about where you invest. So even 5 to 6 per cent is already enough to help cover expenses. The important thing is — don’t have nothing at all.”
Uzir also stressed the importance of cultivating saving habits from the outset of one’s career.
“When you start working, there should already be a concept of saving — even 5 per cent, 3 per cent — something consistent,” he said.
At the same time, he warned that the widespread adoption of QR code payments is subtly altering spending behaviour, removing traditional constraints associated with cash transactions.
“The problem now is QR codes — they are quite kacau (disruptive),” he said.
“Before this, when we used cash, we only brought a small amount. When it’s finished, that’s it. Now with QR, everything is easy.
“When you see someone show a QR code, you also feel like using it.
“Even when you don’t really need to buy something, you still end up paying.”
The ease of digital payments, he suggested, has shifted spending from deliberate decision-making to near-automatic behaviour.
“Before, we were more prudent because we had to think about the cash in our pocket. Now, the barrier is gone.”
Despite these challenges, Uzir maintained that technology itself is not the problem, but rather how individuals adapt to it.
“The tools have changed, but the principle is the same,” he said.
“If we don’t control our spending, our surplus will disappear.” - April 29, 2026